
Make the Right Choice at the End of Your PCP Deal With Our Advice…
PCP can be a great way to get into a nicer, newer car than you might otherwise afford to buy outright or through Hire Purchase (HP). With a large proportion of the car's cost deferred until the end of the agreement, monthly payments can be more manageable, although there's a little more to consider than simply choosing a car and paying for it.
Unlike buying outright or using traditional HP, PCP gives you several choices when your agreement finishes. You can buy the car, trade it in for something different or hand it back and walk away.
But which is best for you? Is PCP actually worth it in the long run? And what happens if your car is worth more or less than the final payment?
In this article, we'll look at the three main options, the potential costs involved and a few things worth checking before making your decision.
First, though, let's cover some of the basics of PCP.
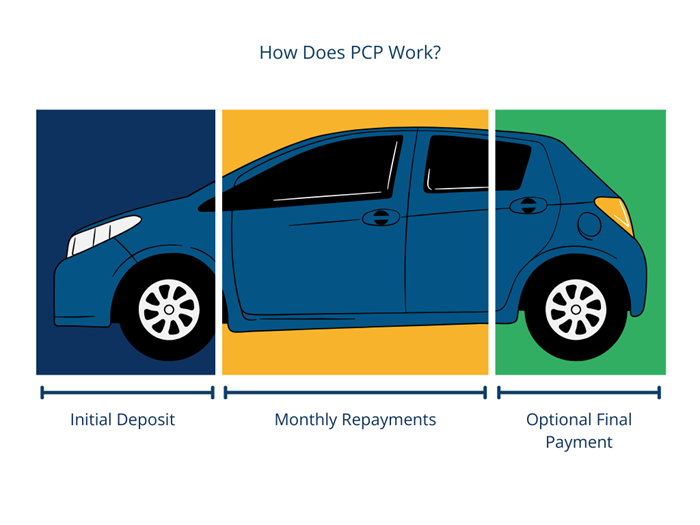
How Does PCP Work?
Personal Contract Purchase (PCP) is a type of car finance that usually involves three stages: an initial deposit, regular monthly payments and an optional final payment, sometimes referred to as the balloon payment.
Unlike traditional HP, where your monthly payments generally cover the cost of the vehicle (plus interest and any fees), PCP defers a significant amount until the end of the agreement.
This amount is based on the car's predicted future value, often referred to as its Guaranteed Future Value (GFV).
The result? Your monthly payments can be lower than those of a comparable HP agreement, although that doesn't necessarily make PCP cheaper overall.
As you reach the end of your PCP term, you have three main options:
-
Buy the car: Pay the optional final payment, along with any applicable purchase fee, and own the vehicle outright.
-
Trade the car in: Use any positive equity towards another vehicle, whether that's through a new PCP agreement or a different way of buying.
-
Hand the car back: Return the vehicle under the terms of your agreement without paying the optional final payment, subject to any applicable mileage, damage or other contractual charges.
There's also the possibility of refinancing the final payment if you'd like to keep the car but don't have the money available to buy it outright.
For a useful independent explanation of how deposits, monthly instalments and balloon payments work together, MoneyHelper's guide to buying a car with PCP covers the basics in more detail.
How Does the PCP Final Payment Affect Your Options?
One of the biggest attractions of PCP is the relatively low monthly payment compared with some other forms of car finance. However, it's important to understand why those payments can be lower.
With PCP, you're not paying off the entire cost of the car through your regular instalments. Instead, a substantial amount is left until the end.
Generally speaking, the larger the amount deferred, the lower your monthly payments can be, although the deposit, interest rate, agreement length and vehicle price will also affect what you pay.
For example, imagine you're financing a car worth £20,000 with a £2,000 deposit and an optional final payment of £9,000.
Over the agreement, your monthly payments will cover the financed amount not deferred to the end, together with the applicable interest and charges. If you decide to keep the car, you'll still need to find the £9,000 final payment.
That's an important consideration if you think you're likely to buy the vehicle at the end.
Our Advice: Don't choose a PCP deal based purely on the monthly payment. Look at the total amount payable, the optional final payment and how you intend to fund it if you want to keep the car.
A deal that looks affordable today might be less attractive if you're faced with a large payment in three or four years.
Is PCP Worth It?
It's a fair question, particularly if you've spent several years making monthly payments and still don't own the car.
The answer depends on what you want from your vehicle and how you intend to pay for it.
PCP can work well if you like driving a relatively new car, prefer to change vehicles every few years and want the flexibility to decide whether to buy or return it at the end.
However, if your aim is to own a car for many years without ongoing finance payments, PCP might not be the most cost-effective route.
PCP Pros and Cons
| Potential Advantages | Things to Consider |
|---|---|
| Monthly payments can be lower than comparable HP agreements | A large optional final payment is required if you want to own the car |
| You can choose to buy, return or trade in the car | Mileage limits and return-condition requirements apply |
| You can change vehicles regularly | Repeated agreements can mean years of ongoing monthly payments |
| Manufacturer or dealer deposit contributions may be available | The total cost of finance may be higher than alternatives |
| Positive equity could contribute towards your next car | Negative equity can make changing cars early more expensive |
| The optional final payment gives you a choice about ownership | You don't automatically own the vehicle at the end |
Is PCP a Waste of Money?
Not necessarily, although it can become expensive if you're regularly changing cars without considering the long-term cost.
For example, someone who takes out a new PCP every three years might enjoy driving newer vehicles with fewer age-related maintenance concerns.
On the other hand, someone who buys a reliable car outright and keeps it for eight or ten years may spend considerably less on purchasing and financing vehicles over that period.
Neither approach is automatically right or wrong.
The problem comes when PCP is treated as a way of getting a more expensive car for a smaller monthly payment, without considering the deposit, interest, final payment or cost of starting another agreement.
Our Advice: If you're happy changing cars regularly and can comfortably afford the full cost of doing so, PCP could be a sensible option. If you're looking to minimise your long-term motoring costs, it's worth comparing PCP against HP and buying outright.
Is PCP Better Than Buying a Car Outright?
Buying outright is certainly simpler. Once you've paid for the vehicle, it's yours. There are no finance-related mileage restrictions, optional final payments or monthly instalments.
However, buying outright also means finding the full purchase price upfront, which could tie up a significant amount of your savings.
PCP spreads much of the cost over several years and gives you the choice of returning the car rather than buying it.
The trade-off is that you'll pay interest on the finance, remain subject to the agreement's conditions and won't own the car unless you complete the purchase.
If you intend to keep a vehicle for many years, buying outright may work out cheaper. If you prefer to change cars regularly, PCP may offer the flexibility you're looking for.
MoneyHelper's comparison of different ways to finance a car is worth a look if you're deciding between PCP, HP, leasing and buying outright.
Whichever you choose, compare the overall cost rather than just the monthly payment.
Your PCP End-of-Term Options at a Glance
Before we look at each option in detail, here's a quick comparison of what happens when your agreement finishes.
| Your Option | What Happens | Worth Considering If… |
|---|---|---|
| Buy the car | Pay the optional final payment and any applicable purchase fee to become the owner | You like the car, know its history and want to keep it |
| Trade in or upgrade | The finance is settled and any positive equity can go towards another car | You want something newer or your circumstances have changed |
| Return the car | Hand the vehicle back under the agreement's return conditions | You no longer need it or don't want to continue financing |
| Refinance | Arrange new finance to cover the final payment | You want to keep the car but can't or don't want to pay the lump sum |
There's no universally best option. Your decision will depend on the car's value, its condition, your finances and what you want to drive next.
Should You Buy, Return or Upgrade at the End of Your PCP Deal?
Whether you exchange, buy or give up your car at the end of your agreement is a personal choice, with benefits and drawbacks to each.
Before you make a decision, it pays to understand the pros and cons so you get it right, without any regrets and, if applicable, get the best deal for you.
Here's a breakdown of each option.
Is It Worth Buying Your Car at the End of PCP?
Paying the optional final payment and owning the car outright can be a good idea if you're happy with the vehicle and want to avoid committing to another PCP agreement.
Once you've bought the car, you're free from the mileage and return-condition restrictions associated with PCP. You can keep it as long as you like, modify it if you wish and eventually sell it whenever you choose.
You also know the car's history. If you've looked after it, kept up with servicing and had no major reliability problems, that familiarity can be worth something.
However, there are a few things to consider before paying the final amount.
If you decided to purchase your car outright, consider Agreed Value Gap Insurance for ongoing peace of mind.
Is the car worth more than the final payment?
This is probably the most important question.
If your optional final payment is £8,000 and similar cars are selling for £10,000, buying it could make financial sense, particularly if you intend to keep it.
However, if the car is only worth £6,500, you need to think carefully about paying £8,000 for something you could potentially buy for less elsewhere.
Remember that advertised prices aren't necessarily what your own car would achieve as a trade-in or private sale.
Will the car still suit your needs?
Perhaps you bought a small hatchback three years ago but now need something with more space. Or maybe your annual mileage has increased significantly.
If the car no longer suits your circumstances, paying to keep it might not be worthwhile, even if the final payment looks reasonable.
What about maintenance and repairs?
One of the advantages of driving a relatively new car is that major repairs may be less likely, and some faults may be covered by a manufacturer's warranty.
As your vehicle gets older, you'll need to budget for servicing, MOTs, tyres and potentially more expensive mechanical repairs.
That doesn't mean buying your PCP car is a bad idea. In fact, keeping a well-maintained vehicle can be considerably cheaper than repeatedly replacing it.
But it's worth looking at the costs you're likely to face over the next few years.
Our Advice: Before paying the optional final payment, get an up-to-date valuation for your car and compare it against the amount required to buy it. Then consider the cost of keeping it for another two or three years against the cost of replacing it.
Don't assume a new PCP is automatically better just because the monthly payment looks manageable.
Trade In or Upgrade Your PCP Car
If you don't want to own the car you're currently driving, you could trade it in towards another vehicle.
For many PCP customers, this is the most familiar option. You reach the end of your agreement, visit the dealership and choose something newer.
In some cases, dealerships or manufacturers may offer incentives, discounts or deposit contributions to encourage you to take out another agreement.
However, there's no guarantee that your next car will cost roughly the same each month.
Vehicle prices, interest rates, deposits and finance terms can all change. Even if you're buying a similar model, you might find yourself paying considerably more than you did three or four years ago.
One of the benefits of trading in is that you can move into a newer car, potentially with a manufacturer's warranty and fewer immediate maintenance concerns.
It's also an opportunity to choose something that better suits your needs.
On the downside, you're committing to another finance agreement, along with its mileage restrictions, return-condition requirements and monthly payments.
If you're continually taking out new PCP agreements, you could find yourself making car payments indefinitely without ever owning a vehicle.
Our Advice: Before discussing your next car, find out what your current vehicle is worth and, if the finance is still outstanding, request an up-to-date settlement figure.
This will help you understand whether there's any positive equity available towards your next deposit.
It's also worth comparing offers from more than one dealership. A generous part-exchange allowance isn't necessarily a good deal if the replacement car is overpriced or the finance terms are poor.
And don't forget to compare the total amount payable, not just the monthly instalment.
Return Your PCP Car
Returning the car at the end of your agreement can be one of the simplest options, particularly if you no longer need it or don't want to take out another finance agreement.
With PCP, the optional final payment is based on a Guaranteed Future Value agreed at the start of the contract.
If you choose to return the car at the scheduled end of the agreement, you generally won't need to pay that final amount, provided you've met your contractual obligations.
This can be particularly useful if the car has depreciated more than expected and its current market value is lower than the optional final payment.
Rather than paying more than the car is worth to buy it, you can return it under the agreement.
However, handing the car back doesn't necessarily mean there will be nothing else to pay.
Your finance provider will normally inspect the vehicle for damage and check its mileage against the agreed allowance.
Excess mileage, damage beyond the permitted return standards and any other outstanding contractual charges could leave you with an additional bill.
Minor wear and tear is generally expected, but damage such as heavily kerbed alloys, significant dents, damaged upholstery or missing equipment could be chargeable.
You should also check that servicing and other agreement requirements have been met.
Our Advice: Don't leave the inspection until the day you return the car.
Check the finance provider's return standards in advance and give yourself time to deal with any damage or missing items.
The BVRLA's Fair Wear and Tear guidance is a useful starting point for understanding the difference between everyday use and damage that may result in charges, although your own finance provider's standards and agreement terms will apply.
If you've exceeded your agreed mileage, ask your finance provider how the charges will be calculated. Some agreements may allow mileage arrangements to be amended, but this isn't guaranteed.
It's also worth checking whether the car has any positive equity before handing it back. If it's worth more than the final payment, you may have other options that are financially more attractive.
Can You Refinance the PCP Final Payment?
If you're enjoying your current car but don't have the money available to pay the optional final payment, refinancing may be worth considering.
Rather than paying the full amount in one lump sum, you arrange another loan or finance agreement to cover the cost.
For example, if your optional final payment is £9,000, you might choose to finance that amount over another two or three years.
This allows you to keep the car while spreading the cost.
Depending on the finance arrangement, you may also become the legal owner once the original PCP is settled, although a new secured finance agreement could still place restrictions on the vehicle.
Refinancing can be attractive if you're happy with the car and don't want to replace it simply because your agreement is ending.
However, don't forget that you're extending your borrowing.
You'll need to consider the new interest rate, monthly payments, fees and total amount repayable.
A smaller monthly payment over a longer period could mean paying more interest overall.
Our Advice: Compare refinancing against a personal loan, using savings or changing the car. If the vehicle is worth less than the final payment, think carefully before borrowing more than its current value to keep it.
What If Your Car Is Worth More Than the PCP Final Payment?
One of the more confusing parts of PCP is the idea of equity.
Put simply, positive equity means your car is worth more than the amount needed to settle the outstanding finance.
At the scheduled end of your agreement, this is often a comparison between the vehicle's current value and the optional final payment, together with any applicable fees or outstanding amounts.
For example:
| Amount | |
|---|---|
| Current car value | £12,000 |
| Optional final payment | £9,000 |
| Potential positive equity | £3,000 |
In this example, there's potentially £3,000 of value in the vehicle above the final payment.
That doesn't mean your finance company will automatically give you £3,000 when the agreement ends.
Instead, you may be able to use that equity towards another vehicle by arranging a part-exchange in which the outstanding finance is settled.
Alternatively, you could buy the car and then sell it, although you'd need to account for any fees and the price you can actually achieve.
If you simply return the vehicle under the standard end-of-agreement option, you would not normally receive that positive equity.
This is why it's worth checking your car's value before handing it back.
Our Advice: Get more than one valuation. Compare what a dealership will offer in part-exchange against realistic market values, and remember that the highest advertised retail price isn't necessarily what your car is worth.
If you're planning to sell the car while finance is outstanding, make sure the finance provider's settlement and sale requirements are followed.
What Happens to Your Deposit at the End of PCP?
Another common question is whether you get your deposit back when your PCP agreement finishes.
In most cases, the answer is no.
Your initial PCP deposit isn't normally a refundable security deposit. It's an upfront contribution towards the vehicle's purchase price, reducing the amount you need to finance.
When you return the car, that original deposit isn't automatically refunded.
However, if your car has positive equity, you may be able to use that value towards the deposit on your next vehicle.
This is where some of the confusion comes from.
Dealerships sometimes describe positive equity as money towards your next deposit, but it's not the same as getting your original deposit back.
For example, you might have paid £3,000 upfront when you first took out your PCP.
Three years later, your car might have £2,000 of positive equity.
That £2,000 could potentially contribute towards your next car, but it doesn't represent a refund of your original £3,000.
Likewise, there's no guarantee you'll have any equity at all.
Our Advice: If you're relying on equity to fund your next deposit, check the figures before choosing a replacement car. You may need to contribute additional money to keep your monthly payments affordable.
Negative Equity and PCP
Negative equity is a concern for many car owners who are financing a vehicle, including those on PCP.
Cars generally lose value over time, and sometimes they depreciate faster than the outstanding finance balance reduces.
When this happens, you could owe more than the vehicle is worth.
For example:
| Amount | |
|---|---|
| Current car value | £10,000 |
| Finance settlement figure | £12,000 |
| Negative equity | £2,000 |
In this example, selling or trading in the car for £10,000 wouldn't provide enough money to settle the £12,000 finance balance.
You'd need to find the £2,000 difference or make other arrangements with the finance provider.
However, how negative equity affects you depends on whether you're changing your car early, returning it at the scheduled end or dealing with a total loss.
Negative Equity at the End of PCP
One of the benefits of PCP is that you have the option to return the car at the scheduled end of the agreement rather than paying the optional final payment.
If the vehicle is worth less than the final payment, this can work in your favour.
For example, imagine your optional final payment is £9,000, but the car's market value has fallen to £7,500.
Buying the car would mean paying £9,000 for something currently worth around £7,500.
However, if you return the vehicle under the agreement's end-of-term conditions, you generally won't have to make up that difference.
You may still be responsible for excess mileage, damage beyond the permitted standards or other charges under your agreement.
It's important to distinguish these charges from negative equity.
The GFV doesn't guarantee a particular trade-in price or protect you against every possible cost. It provides the basis for the optional final payment and contractual return option.
Our Advice: If your car is worth less than the final payment, don't automatically assume you need to buy it or trade it in. Check the return conditions first, as handing it back may be the more sensible option.
Negative Equity When Changing Your PCP Car Early
Many people decide to change their PCP car before the agreement finishes, often because they've spotted something newer or their circumstances have changed.
However, ending a PCP early can be more complicated.
During the earlier stages of an agreement, your car may have depreciated faster than you've reduced the outstanding finance.
This can leave you in negative equity.
Some dealerships may offer arrangements that allow you to change cars despite this shortfall, but the money doesn't simply disappear.
You may need to pay the difference yourself, or the cost could be incorporated into a new finance arrangement where permitted.
Either way, it can make your next car considerably more expensive.
Our Advice: Before changing early, request a settlement figure from your finance provider and compare it against your car's current value.
Don't assume that changing early is always expensive, or that waiting until the end is always best. The figures will depend on your agreement and the car's value.
You may also have rights to voluntarily terminate a qualifying regulated PCP agreement, subject to the relevant conditions and payment thresholds. This is different from simply settling the finance early or returning the car at the scheduled end.
For more on your options, read our guide to steps to take before the end of your PCP agreement.
Accident, Fire or Theft (Total Loss)
Another situation where negative equity can become a problem is when your car is declared a total loss following an accident, fire or theft.
If your motor insurer writes off the vehicle, they'll generally offer a settlement based on its market value immediately before the loss, subject to the policy terms.
However, if your car is on PCP, the amount paid by your motor insurer might be less than the outstanding finance settlement.
For example, if your insurer pays £11,000 but the finance settlement figure is £13,000, you could be left with a £2,000 shortfall.
This is one reason some drivers consider Gap Insurance.
Depending on the policy, Gap Insurance can help cover certain financial differences following an insured total loss, although the cover available, exclusions and claim limits vary.
For example, Return to Invoice Gap Insurance is designed to cover the eligible difference between the motor insurer's settlement and the original vehicle invoice price or, where applicable under the policy, a higher outstanding finance balance.
If you're unsure which type of cover may be suitable, our guide to Gap Insurance for PCP cars explains the differences in more detail.
Our Advice: If you're buying a car on finance, consider the risk of a total loss and whether suitable Gap Insurance would be worthwhile for your circumstances. Check the cover carefully rather than assuming every policy will pay off any remaining finance.
Can You Change a PCP Car Before the Agreement Ends?
Yes, you can potentially change your car before your PCP agreement finishes, although the options and costs will depend on your finance agreement.
You might be able to settle the outstanding finance and sell or part-exchange the vehicle, or you may qualify for voluntary termination under the relevant consumer credit rules.
The important thing is understanding what you'll owe and whether your car is worth enough to cover it.
Changing early simply because a dealership offers you another attractive monthly payment isn't always the best financial decision.
If you're considering a change, start with your settlement figure, get a realistic valuation and check your agreement's terms.
MoneyHelper's guidance on ending a car finance agreement early explains the difference between early settlement and voluntary termination, including the conditions that apply.
That will give you a much clearer picture of your options before committing to another car.
Before Deciding What to Do at the End of PCP
As your agreement approaches its end, it's worth taking a little time to review your position.
You don't need to make a decision the moment a dealership contacts you about upgrading.
Instead, work through the following checklist:
-
Check your optional final payment. How much will you need to pay if you want to keep the car?
-
Get a current valuation. Find out what the vehicle is realistically worth.
-
Check your equity position. Is the car worth more or less than the amount needed to settle the finance?
-
Review your mileage. Have you stayed within your agreed allowance?
-
Inspect the car's condition. Are there any repairs worth considering before returning it?
-
Check servicing and maintenance. What work might the car need over the next couple of years?
-
Consider your circumstances. Do you still need the same type of vehicle?
-
Compare the cost of keeping and replacing it. Don't just compare monthly payments.
-
Check your next deposit. If you're trading in, will any equity cover it, or will you need more money?
-
Read the finance terms. Make sure you understand the total amount payable before agreeing to another deal.
It's also worth checking when your finance provider needs to know your decision. Don't assume you can leave everything until the final payment date.
A little preparation can help you avoid unnecessary charges, make better use of any equity and choose the option that works best for you.
So, Should You Buy, Return or Upgrade Your PCP Car?
As we always say, don't shy away from PCP simply because the options at the end can seem a little daunting.
For the right driver, PCP can offer a convenient way to finance a newer vehicle, with the flexibility to decide what happens when the agreement finishes.
However, it's not automatically the cheapest way to buy a car, and there's no reason to start another PCP agreement simply because your current one is ending.
Buying the car could be the right choice if you're happy with it, know its history and can comfortably afford the final payment. If it's worth more than the amount required to buy it, keeping it could be particularly attractive.
Trading in or upgrading might make sense if your circumstances have changed, you want something newer or you've built up positive equity that could contribute towards another vehicle. Just remember that a new car means a new financial commitment.
Returning the car could be the better option if you no longer need it, want to move away from monthly finance payments or the vehicle is worth less than the optional final payment. Just make sure you've checked the mileage and return-condition requirements.
And if you'd like to keep the car but can't afford the final payment in one go, refinancing may be an option, provided the additional borrowing makes financial sense.
Ultimately, the best decision isn't necessarily the one that gets you into the newest car or gives you the lowest monthly payment.
It's the one that makes the most sense for your circumstances, your budget and how you intend to use the vehicle over the next few years.
Before committing, check your car's value, understand the final payment or settlement figure and compare the overall costs of each option.
That way, whether you buy, return or upgrade, you'll know you've made an informed decision.
If you've enjoyed reading, please share this article with your friends and on social media. And, as always, if you have any questions, feel free to get in touch with Luke. Drop him a DM on social media and he'll be happy to help.